

In the second half of 2026, the global coffee market is at an unusual stage: production is growing, coffee shop scale is expanding, and the supply chain is also changing. After four consecutive coffee seasons of shortage, the International Coffee Organization (ICO) expects a surplus in the 2025/26 coffee year: production could reach 183.6 million bags (60 kg each), while consumption will reach 180.6 million bags.
Supply is set to grow by 4.4%, while consumption will decline by about 0.8%. Robusta coffee will be the main contributor to production growth: its output is expected to be 79.2 million bags, up 6.5% year-on-year.
This situation is particularly important for the Asian market. The region is no longer viewed merely as an area with consumption growth potential. Coffee production is expanding, the number of coffee shops is growing, unique chain models are emerging, automation technology is advancing, and new models that can be replicated beyond a single country are appearing.
It is precisely this structural reorganization—from raw materials to final sales—that is shaping the current state of the Asian coffee market. The B2B market is focusing on all links in this chain: raw materials and roasting, equipment, coffee shop solutions, ingredients, packaging, and new products.
These areas are closely aligned with the professional agenda of the 2027 Asia Coffee Shop Supply Chain Exhibition. The editorial team of B2B Media, together with the exhibition organizers, discussed the changes taking place in the Asian coffee industry, the processes shaping its development, and what these processes mean for supply chain participants.
In Asia, coffee is becoming an independent industry.
The growth in the scale of coffee shops is already evident. According to World Coffee Portal data, the branded coffee shop market in East Asia grew by 18.4% over the past year, reaching 180,268 outlets. Among them, China has 87,505, South Korea 40,979, and Thailand 11,279. China added more than 20,000 coffee shops last year, while Thailand, Indonesia, Vietnam, and the Philippines also achieved double-digit growth.
But more important than the number of stores themselves is that the region is gradually forming its own coffee economy.
China is simultaneously expanding its domestic coffee production. By 2025, Yunnan Province's coffee planting area will reach 1.463 million mu (approximately 97,500 hectares), with green coffee production reaching 138,900 tons. The province has established a complete industrial chain from breeding and planting to processing and sales, with the deep processing ratio reaching 80%.
Vietnam's development is different. According to data released by the Vietnam Coffee and Cocoa Association (VICOFA) in September 2026, in the first eight months of 2026, Vietnam exported nearly 1.7 million tons of coffee, generating over 6 billion USD in revenue. Although actual shipments increased by more than 10% year-on-year, export revenue fell by 11.2% due to falling average prices.
This has resulted in an obvious gap: physical supply has increased, but the value captured by exporters may be moving in the opposite direction.
For the Asian market, this is more important than the latest growth forecasts. The question is gradually shifting from how much coffee is produced and sold to at which link in the supply chain added value is created.
India offers another combination: large-scale production, exports, and a growing domestic market. According to the Coffee Board of India, the final production estimate for 2025/26 is 373,400 tons, while the preliminary estimate for 2026/27 is approximately 404,100 tons.
Thus, a new landscape for Asian coffee is gradually taking shape: some countries are increasing both production and consumption, others are strengthening exports, and still others are becoming major sales markets.
China is not only expanding the scale of its coffee shops, but also its business models.
The Chinese market clearly shows that rapid growth in the number of stores is no longer the main event in itself.
By the end of the second quarter of 2026, Luckin Coffee had a total of 36,310 stores. In that quarter, Luckin Coffee opened 2,714 new stores, with average monthly transactions reaching 112.7 million. Revenue grew by 28.5% year-on-year.
However, same-store sales for the company's own stores fell by 5.3%. The company attributed this to factors such as last year's high base and changes in delivery platform subsidy terms.
For the market, this is more important than record coffee shop numbers. Chain store expansion is no longer a sufficient condition for growth. Operators must constantly weigh the price per cup, customer acquisition costs, delivery costs, store rent, and personnel costs.
As a result, there is strong interest in automation, centralized control, and standardization.
In China, automation application is no longer limited to individual operational links. In August 2026, JD.com opened a 24-hour automated coffee shop in Beijing, where all beverage preparation processes are completed by robotic systems.
South Korea's move toward automation has different reasons. Rising labor costs and staff shortages are prompting companies to turn to self-service kiosks, self-checkout, and robotic operations. According to payment system data cited by the Seoul Economic Daily, the number of unmanned stores in South Korea is expected to reach approximately 12,000 by 2026. Meanwhile, official statistics from the National Fire Agency of South Korea show that by 2024, the number of such stores was around 9,030, covering only some formats.
This creates a peculiar divergence. In China, automation helps scale standardized models; in South Korea, automation becomes a means to compensate for labor shortages. The technology is the same, but the economic reasons are completely different.
For suppliers, this means a shift in demand. Today, equipment is no longer evaluated in isolation from the business, but rather in terms of its impact on productivity, headcount, and cost per outlet.
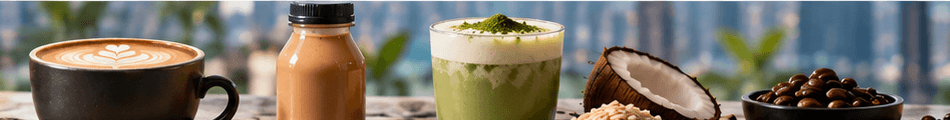
The next stage of competition will revolve around products, not just spaces.
The growth of Asia's coffee industry is not only reflected in quantity; its sales formats are also constantly changing, with the ready-to-drink (RTD) coffee market being particularly prominent.
In Japan and South Korea, RTD coffee has long been an independent category, and major coffee chains use RTD beverages to expand brand influence beyond their own stores. In China, this trend is also playing out with the rapid development of chain stores and delivery channels.
As a result, the coffee brand gains the opportunity to compete simultaneously in multiple arenas:
-Cafés;
-Delivery;
-Ready-to-drink beverages;
-Retail shelves;
-Seasonal and local specialty menus.
For ingredient suppliers, this means shorter R&D cycles. Not only do beverage flavors change, but requirements for formula stability, ingredient delivery times, packaging, and the ability to rapidly scale successful products also change.
However, the development trajectories of Asian markets are not uniform. In China, the affordable chain store model featuring small stores, delivery, and low prices has developed particularly prominently. In South Korea, coffee shop density is high, competition is fierce, and automation models are spreading rapidly. The Japanese market is more mature, and its growth model differs from China's. World Coffee Portal notes that despite overall economic growth in East Asia, the number of branded coffee shops in South Korea grew by only 6.6%, while Japan grew by 2.6%.
Therefore, the concept of the "Asian coffee market" is becoming increasingly heterogeneous.
What is happening in the supply chain?
At first glance, coffee bean production, coffee shops, robotic equipment, and finished beverages may seem independent of one another. But in reality, they are increasingly interconnected.
If a supply chain expands rapidly, it requires stable raw materials and standardized formulas. If the product range changes faster, ingredient suppliers must shorten R&D cycles. If labor costs rise, equipment costs will also be factored in. If the chain expands into RTD products, coffee must also meet the requirements of industrial formulation, packaging, and logistics.
Climate risk also brings uncertainty to the production side.
As a result, the Asian coffee industry is gradually shifting from a model where each player optimizes their own link to one where consistency across the entire chain—from green coffee beans to the final beverage—is paramount.
This leads to the most interesting question in the B2B market: to what extent can suppliers adapt to specific national models?
There is no unified standard in the Asian market. A Chinese chain with tens of thousands of stores has one set of needs; a South Korean automated coffee shop has another; coffee producers in Vietnam or Indonesia are solving completely different problems; and the mature Japanese market requires a different set of solutions.

The market is about to enter 2027, but no unified forecast scenario has emerged yet.
The global coffee market is currently moving toward restoring supply-demand balance. Asia remains one of the largest coffee consumption and production centers, but the balancing process within Asia is much more complex.
Several changes are happening simultaneously:
-Production is shifting toward consumers;
-Large networks can scale;
-Individual coffee shops are finding operations increasingly difficult;
-Automation is no longer experimental;
-The scope of coffee extends far beyond traditional coffee shops;
-Suppliers are forced to adapt to local markets faster.
Therefore, the key question facing the Asian coffee industry in the near term is no longer just the speed of consumption growth, but rather how value is distributed in the new coffee supply chain, and who can ensure their sustainable development amid rapid change.
We would like to share an insightful article from our media partner, a B2B-media about retail and horeca trade, "Point of Sale". Read the full article here: https://tpmag.ru/articles/horeca/aziatskij-ryinok-kofe-2026-2027/